

SAP Concur warns of rising fraud losses in finance
Fri, 20th Nov 2026 (Today)
SAP Concur has released research showing low confidence among finance and accounts payable professionals in their organisations' fraud defences. The study found that 62 per cent of respondents had suffered financial losses from fraud in the past three years.
The Finance Leaders' Fraud Report 2026 surveyed finance and AP professionals globally and highlights a widening gap between fraud exposure and confidence in existing controls. Just 22 per cent of respondents said they felt very well protected against fraud.
The most commonly reported incidents were business email compromise, cited by 45 per cent of respondents, and impersonation fraud, cited by 40 per cent. The findings also suggest fraud methods are evolving, with six per cent of respondents reporting deepfake audio fraud and another six per cent deepfake video fraud.
According to the research, impersonation fraud rose from 35 per cent in 2025 to 40 per cent in 2026. That trend adds pressure on finance teams responsible for checking payment requests, supplier details and other transactions.
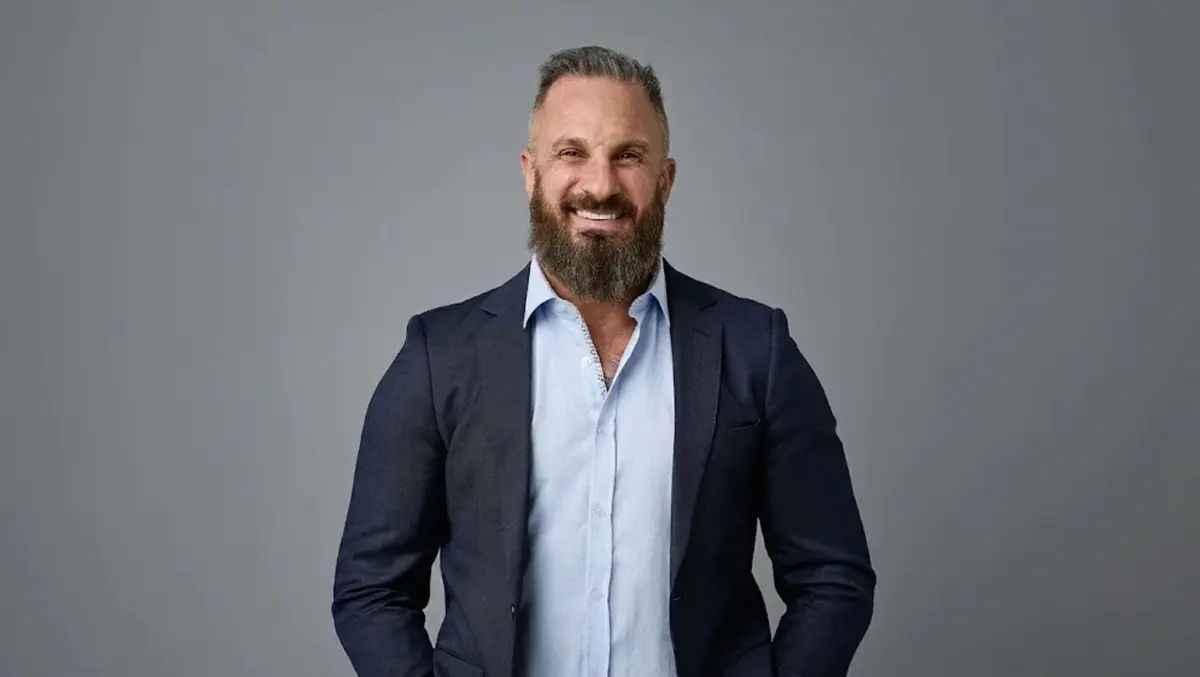
Fabian Calle, Managing Director, SAP Concur Australia and New Zealand, said: "Fraud is becoming harder to detect as criminals use increasingly sophisticated methods to exploit weaknesses in financial processes. Finance leaders can no longer rely on traditional approval workflows and manual checks alone. They need greater visibility into spending, stronger controls, and the ability to identify suspicious activity before it results in financial losses.
"Businesses of all sizes face these challenges, though smaller finance teams can be particularly vulnerable when limited resources make it difficult to review every transaction. Strengthening fraud resilience starts with understanding where risks exist and putting practical safeguards in place."
The report identifies artificial intelligence as one tool finance teams can use to improve oversight. In practice, that includes identifying unusual spending patterns, duplicate invoices and other anomalies across travel, expense and invoice processes.
This approach is presented as a way to reduce reliance on manual checks and let staff focus on higher-risk transactions. Even so, the findings suggest technology alone is not seen as enough.
Calle said: "AI can help finance teams identify potential fraud earlier, though technology alone isn't enough. Organisations need to combine automated controls with clear policies, employee training, and human judgement. The goal is to make suspicious activity easier to identify without creating unnecessary administrative work.
"Connecting travel, expense, and invoice data also gives finance leaders a clearer picture of where money is going. This visibility helps them identify irregularities, strengthen compliance, and make more informed decisions about financial risk."
Training gap
The research also found concerns about management support and staff awareness. Sixty per cent of respondents said they believed their manager could do more to protect their team from AP fraud.
Nearly three in 10 respondents, or 29 per cent, said their organisation does not invest in fraud training or awareness programmes. At the same time, 76 per cent said they would welcome additional training and resources.
Together, these figures suggest fraud prevention is still treated inconsistently across organisations, despite the frequency of reported losses. The findings highlighted regular policy reviews, supplier verification and employee education as areas where businesses can tighten controls.
Smaller finance teams may face particular difficulties, as limited resources can reduce the scrutiny given to each payment or invoice. That leaves organisations more exposed when attackers use tactics designed to mimic legitimate requests or internal approvals.
The findings come as finance functions face a broader shift in fraud risk, from conventional payment scams to more convincing forms of impersonation and manipulated media. For companies, that raises operational as well as technical questions, especially around who approves payments, how exceptions are handled, and what information is checked before money leaves the business.
Calle said: "Fraud resilience depends on people, processes, and technology working together. Finance leaders who invest in visibility, automation, and employee awareness will be better positioned to manage emerging risks while maintaining operational efficiency. Taking a proactive approach to fraud prevention can help organisations protect business resources, strengthen trust, and support sustainable growth."